Brokers Digest: Local Equities - Automotive, Inari Amertron Bhd, Mi Technovation Bhd, Ancom Nylex Bhd
This article first appeared in Capital, The Edge Malaysia Weekly on July 27, 2026 - August 2, 2026
Automotive
OVERWEIGHT
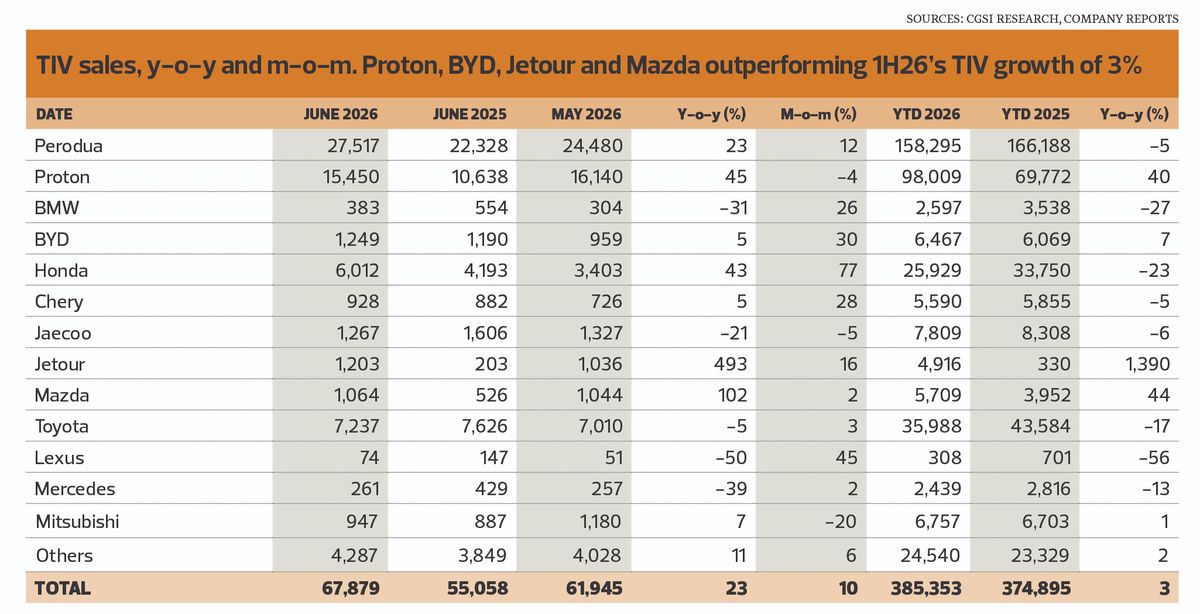
CGS INTERNATIONAL SECURITIES (July 21): The Malaysian Automotive Association (MAA) reported total industry volume (TIV) of 67,879 units for June 2026, up 23% year on year (y-o-y) and 10% month on month (m-o-m). The stronger month was expected, supported by Kuala Lumpur International Mobility Show (KLIMS)-driven demand and broad-based discounting, despite fewer working days.
The m-o-m growth was mainly driven by Honda on heavy discounting, while Perodua was supported by stronger Bezza and Alza sales. 1H26 TIV rose 3% y-o-y to 385,353 units, thanks to the outperformance of Proton (Proton e.MAS, Saga and facelift launches), Mazda (Mazda 3), BYD (beneficiary of stronger demand for electric vehicles [EVs]) and Jetour (Malaysian market share expansion to 1.3% from 0.3% in 2025). According to Road Transport Department (JPJ) data, EV sales increased by 90% y-o-y and 23% m-o-m to 6,215 units in June, with most EV brands recording m-o-m growth ahead of the tighter Completely Built-Up (CBU) EV policy effective July 2026.
1H26 TIV came in stronger than our expectations, supported by new model launches and promotional activities. Given seasonally stronger 2H sales, we raise our 2026F TIV forecast to 780,000 units from 755,000 units, as we expect promotional activity to support 2H26F sales momentum.
We are “overweight” on the auto sector despite expectations for a softer y-o-y TIV, as we believe our “add-rated” stocks — Bermaz Auto Bhd (KL:BAUTO), Hong Leong Industries Bhd (KL:HLIND) and Sime Darby Bhd (KL:SIME) — offer company-specific earnings catalysts. Bermaz is supported by Mazda’s market share recovery and dividends; Sime Darby benefits from EV and mass-market exposure alongside industrial earnings leverage as a longer-term thematic play; while HLI remains underpinned by resilient motorcycle demand, premiumisation and market share gains.
Sime Darby is our sector top pick. Following our recent site visit to Sime’s industrial operations in Brisbane, management remains constructive on the long-term mining outlook, with rebuild activity (after sales) expected to recover in 2HFY27F and equipment sales picking up in FY28F. Sime Darby is also positioned to benefit from potential shifts in demand towards EVs and the affordable mass-market vehicles. It trades at an undemanding 8.7 times CY27F PER (-1 standard deviation from its five-year mean), with CY27F dividend yield of 6.8%.
Inari Amertron Bhd
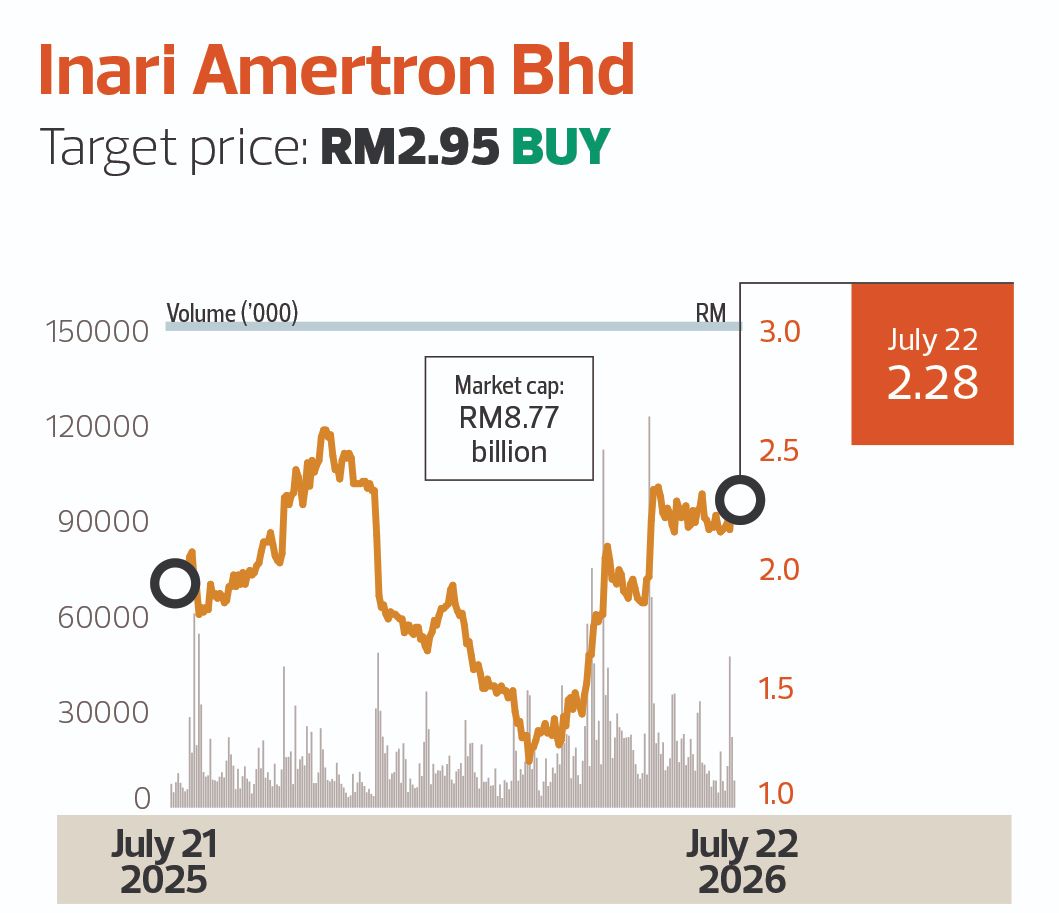
Target price: RM2.95 BUY
MBSB RESEARCH (July 20): We understand that Inari Amertron Bhd’s (KL:INARI) direct customer for the radio frequency (RF) business has signed a multiyear contract with the end customer. This would reinforce the medium-to-long-term visibility of the RF business. Moreover, new smartphone models rollout would carry higher content value (FY27: four circuits versus one circuit previously). This will be made available by moving from single-sided to double-sided mould. The evolution will enable more components in small areas and better RF module integration, which act as a bridge towards advanced packaging. We expect a notable rebound in RF’s loading volume from FY27.
The group’s optoelectronics business has been lacklustre on muted demand. However, there is a strong revival in demand, driven by artificial intelligence-driven optical communications. Inari is well positioned in the supply chain to provide outsourced semiconductor assembly and test (OSAT) services for the optical transceiver module chips. Management has guided that volume will increase exponentially from FY27 onwards.
We make no changes to our earnings at this juncture. We remain confident that FY27 will serve as a strong inflection point for the group with anticipated earnings growth of about 50% y-o-y. Maintain “buy” with an unchanged target price of RM2.95.
Mi Technovation Bhd
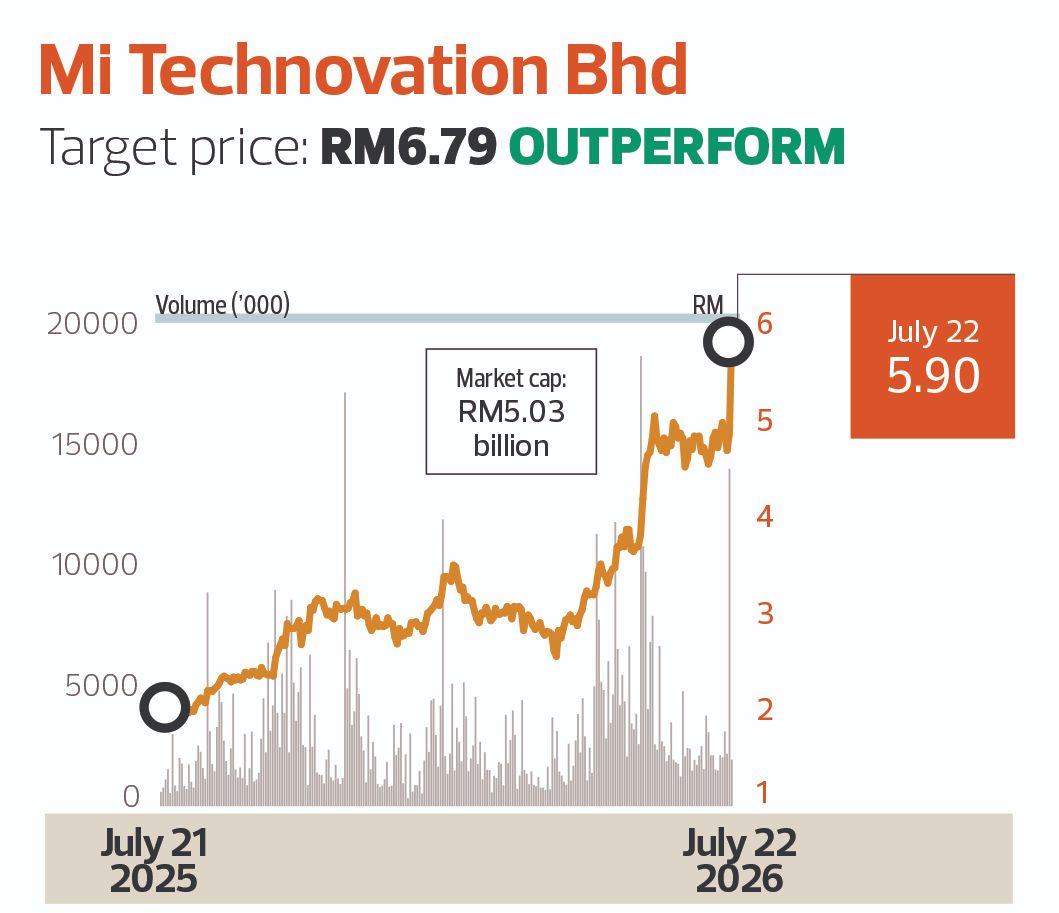
Target price: RM6.79 OUTPERFORM
PUBLICINVEST RESEARCH (July 21): Mi Technovation Bhd’s (KL:MI) 2QFY26 revenue surged 47% y-o-y, bolstered by the semiconductor equipment business unit (SEBU) and semiconductor material business unit (SMBU) segments.
Led by higher capacity utilisation and stronger sales from high-end products, core profit grew from RM28.6 million to RM54.3 million, bolstered by a commendable SEBU performance and a five-fold jump from the SMBU segment. Meanwhile, two new business units remained loss-making as they are still in the gestation phase. Taiwan-based Semiconductor Technologies Business Unit (STBU), which is involved in the silicon carbite metal-oxide-semiconductor-field-effect transistor (SiC MOSFET) business, posted a bigger loss of RM6 million, while the vehicle technology business unit (VTBU) saw its losses narrow from RM2 million to RM0.1 million as sales grew.
Management has set aside higher capex for STBU and VTBU, up from FY25’s RM27 million to between RM50 million and RM55 million as the group ramps up prototype development, customer qualification programme and wafer fabrication. Under the VTBU, it targets deliveries of 45 to 55 powertrain systems this year and has set an ambitious target of 500 units in 2028. The Vanda 1 6in SiC MOSFET wafer is on track to enter commercial production by 1Q2027.
Ancom Nylex Bhd
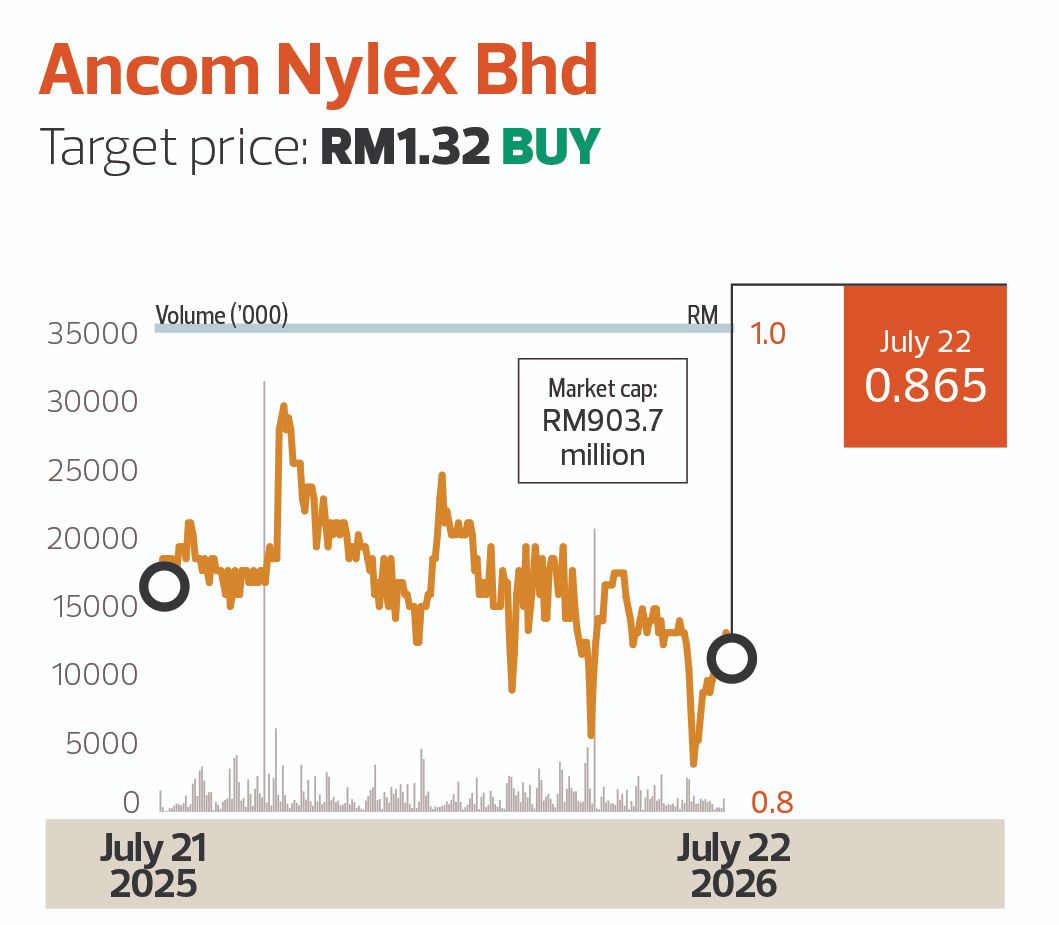
Target price: RM1.32 BUY
HONG LEONG INVESTMENT BANK RESEARCH (July 22): Ancom Nylex Bhd’s (KL:ANCOMNY) 4QFY26 and full-year FY26 core net profit rose 25.3% and 35.6% y-o-y respectively, in tandem with higher revenue of 32.5% and 3% y-o-y, supported by strong performance in the industrial chemicals segment, thanks to higher ASPs and improved operational efficiency. Core net profit margin improved to 4.5% in FY26 versus 3.4% in FY25.
We expect the uplift in the industrial chemicals segment to be largely Brent-driven and therefore likely to moderate from 2QFY27 onwards should crude oil prices ease following any de-escalation in the Iran war.
The Johor e-ART project (Ancom has a stake in the consortium) would provide it with long-term recurring income through equity participation, management fees and operations, and maintenance services under a proposed 20- to 30-year concession. The project is unlikely to contribute meaningfully near term.
Maintain “buy” rating with a higher target price of RM1.32 (from RM1.13) as we roll over our valuation base year to FY27 pegged to 15 times PER. We like Ancom for its niche as the sole large-scale producer of active ingredients (AIs) for herbicides in Asean as AI manufacturing commands high barriers to entry and earnings growth potential driven by its pipeline of new AIs.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.
The content is a snapshot from Publisher. Refer to the original content for accurate info. Contact us for any changes.
Related Stocks
Comments