Talk of Lotte Chemical Titan stake sale surfaces amid uphill turnaround
This article first appeared in The Edge Malaysia Weekly on August 24, 2026 - August 30, 2026
NEWS of a potential stake sale by Lotte Chemical Titan Holding Bhd’s (KL:LCTITAN) major shareholder has piqued market interest in the company after years off investors’ radar screens.
The purported plan involving South Korea’s Lotte Chemical Corp’s (LCC) 75.86% stake in Lotte Chemical Titan comes after nearly five years of losses for the Malaysian-listed firm, one of Southeast Asia’s major producers of naphtha-based plastic polymers.
It also comes as chemical mergers and acquisitions (M&A) activity has picked up, with turnaround investors and consolidators showing greater interest in assets amid a supply squeeze from the Middle East, according to fund managers and analysts contacted by The Edge.
For Lotte Chemical Titan’s minority shareholders, however, the potential corporate exercise offers only a small spark of excitement for the company whose balance sheet is highly geared following its Indonesian expansion, and whose share price has fallen another 40% in the past year.
At the moment, there is “plenty of interest” from independent Chinese refiners — also known as “teapot refineries” — that are having problems procuring feedstock due to the Iran conflict, says an analyst with a regional wealth management firm covering the sector.
“Indonesian buyers like [PT] Chandra Asri [Pacific Tbk] is also actively expanding its footprint,” says the analyst.
Chandra Asri’s deals last year included the acquisition of Chevron Phillips Singapore Chemicals Pte Ltd with its 400,000 tonne-per-annum polyethylene production facility on Jurong Island, as well as Shell Energy and Chemicals Park Singapore, which operates a 1.1 million tpa (mtpa) ethylene cracker on Bukom Island.
Across the wider market, transactions have also taken place in Europe as rising costs prompted owners to revisit their portfolios, while deals have been mooted in the Philippines, Middle East and other parts of Asia since 2025, according to reports.
Lotte Chemical Titan, in a filing with Bursa Malaysia last week, said “LCC is considering various strategic measures” related to the company, which operates 12 plants in Malaysia and seven in Indonesia. No decision has been made by LCC, it said.
Talk of LCC selling Lotte Chemical Titan first emerged in early 2024 and resurfaced again last week.
Lotte Chemical Titan’s flagship operation is its 51%-owned, 1.77 mtpa new ethylene plant in the coastal city of Cilegon, west of Jakarta, which was commissioned in October last year after nearly four years of development from January 2022.
“The biggest value is actually because of the plant location … Lotte Chemical Titan is now better positioned than Middle East producers,” says another analyst covering the sector.
Total investment in the project, dubbed LINE, amounted to US$3.95 billion (nearly RM18 billion), according to an LCC statement last November.
Lotte Chemical Titan listed in 2017 mainly to raise funds for the project. Of the RM3.77 billion raised from its initial public offering (IPO), RM2.59 billion was allocated to LINE, whose construction was awarded to related party Lotte Engineering & Construction.
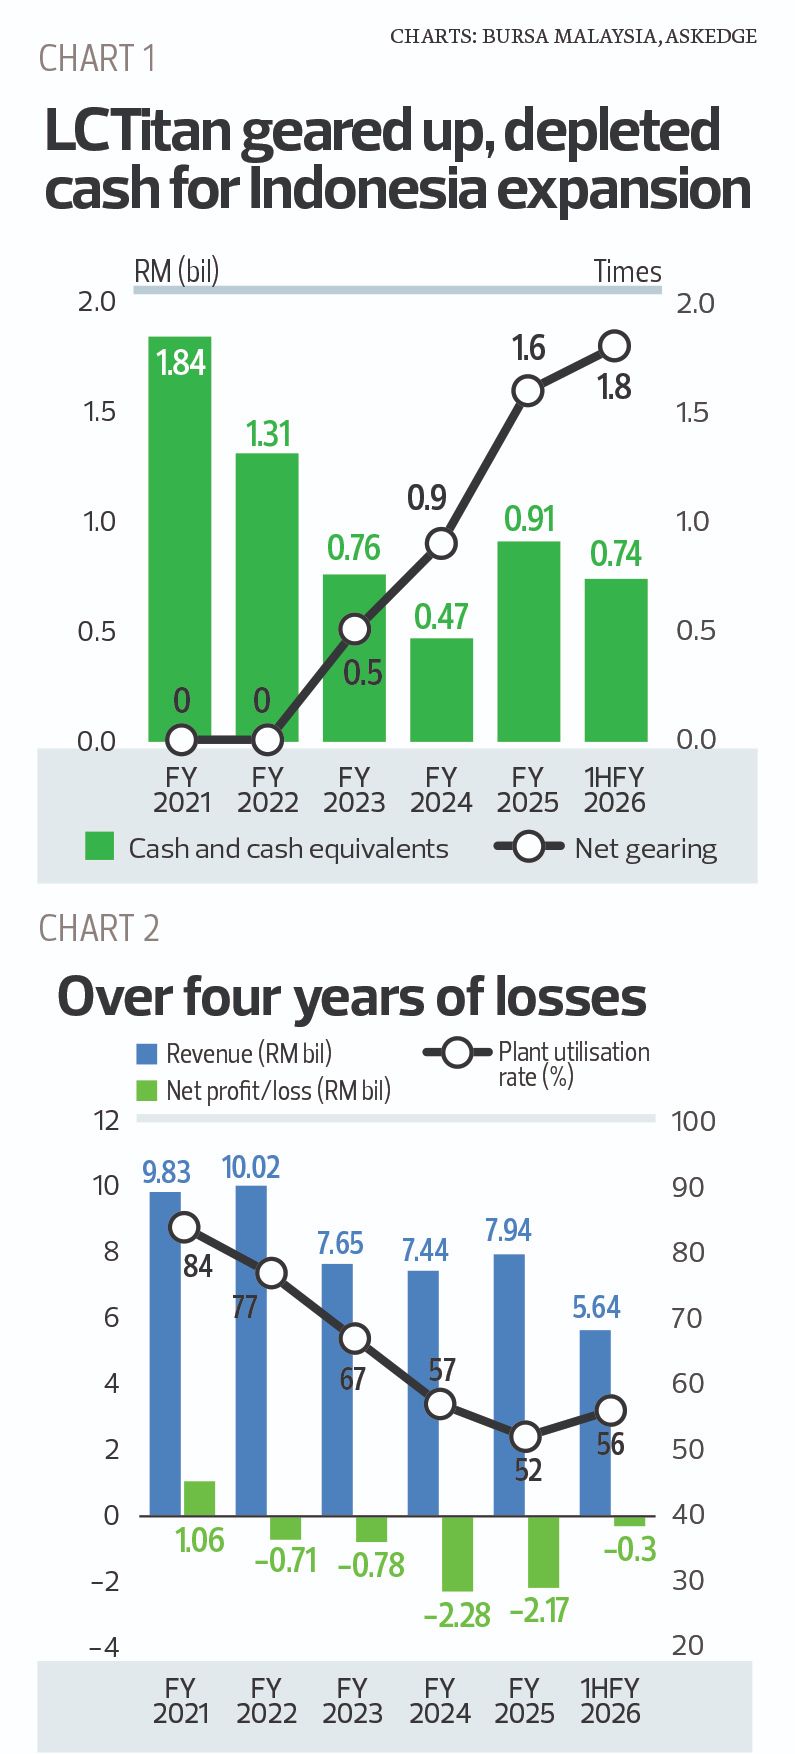
In the process, Lotte Chemical Titan’s cash balance nearly halved from RM1.84 billion as at end-2021 to RM907.6 million in 2025, while borrowings rose to RM11.31 billion at end-2025 from a negligible level over the same period.
The remaining 49% of LINE was held by LCC. However, LCC sold a 25% stake for US$462.7 million last March, leaving it with 24%. According to reports, LCC is also considering disposing of its remaining stake in the project.
LINE was envisioned to boost earnings by raising Lotte Chemical Titan’s total production capacity by 65%. Instead, it came online as the global petrochemical market was grappling with oversupply and weak pricing, adding to Lotte Chemical Titan’s debt and depreciation burden while utilisation remained capped and its core business was bleeding losses.
While it makes sense for Lotte Chemical Titan to rationalise its portfolio amid uncertainty in the petrochemical industry, the M&A market is not pricing in a cyclical recovery, with transaction prices based on current earnings, according to reports.
One example is Chandra Asri’s acquisition of the Shell assets for US$253 million, at a 72.8% discount from its US$933 million book value — although that also reflects the plant’s age of 50 years and the significant capital required to modernise it.
By comparison, Lotte Chemical Titan’s shares closed at 35.5 sen on Aug 21 against net tangible assets per share of RM2.73, according to its latest filing.
The group booked asset impairments and inventory write-downs amid the subdued market as recently as the financial year ended Dec 31, 2025 (FY2025). These added to its losses alongside margin compression and higher depreciation and interest expenses from LINE, even as the project lifted sales.
Lotte Chemical Titan “is still making losses and carries high debt”, says Hang Tuah Amin Tajudin, CEO of unit trust management firm PMB Investment Bhd, which reviewed the company’s prospects following the news. “It looks interesting at its current low valuation, with potential upside [if the deals materalise] … although the turnaround may take time.”
Since FY2022, Lotte Chemical Titan’s net losses have widened every year, from RM714.6 million to RM2.17 billion in FY2025. Asset utilisation fell from 84% in FY2021 to just 52% last year, with a rebound to only 60% to 65% expected this year.
The group’s net gearing has risen to 1.76 times, with net debt of RM10.91 billion, while operating cash flow had yet to turn positive as of the first half of 2026, according to data compiled by AskEdge.
The post-pandemic downturn, marked by subdued demand and oversupply, has affected the whole industry. Even LCC has suffered, with losses entering a fourth year after it posted a net loss of KRW2.05 billion (RM5.9 million) in FY2025, while analysts expect the conglomerate to remain in the red until FY2028.
At home, PETRONAS Chemicals Group Bhd (KL:PCHEM) fell into its first-ever loss of RM2.14 billion, or 27 sen per share, in FY2025, following an impairment on a plant under Swedish unit Perstorp due to rising European costs, alongside foreign exchange losses and weaker margins and earnings across its operations.
For Lotte Chemical Titan shareholders, prospects of a turnaround remain elusive for a stock that has faced multiple setbacks since its 2017 listing.
Mooted as Malaysia’s largest IPO in five years when it was listed, Lotte Chemical Titan had initially planned to raise as much as RM5.9 billion, but cut this to RM3.77 billion by reducing both the offering size and issue price amid lukewarm investor demand. The price was cut to RM6.50 a share from RM8, below even the previously indicated floor. Five cornerstone investors took up 23.5% of the shares — Permodalan Nasional Bhd, Maybank Asset Management Sdn Bhd, Maybank Asset Management Islamic, Eastspring Investments and Great Eastern Life Assurance (M) Bhd.
The stock never traded above its IPO price and has declined over the years to a record low of 28.5 sen in March this year. In all, more than RM14 billion in market capitalisation has been wiped out over its nine years on Bursa Malaysia.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.
The content is a snapshot from Publisher. Refer to the original content for accurate info. Contact us for any changes.
Related Stocks
Comments